
Substack Library
GlossaryWar and AI Are Cuspy
October 11, 2026Not investment advice.
Cuspy is trader talk for “on the cusp,” meaning a small shift in the dynamic can violently shift prices. Today this applies to the war and AI.
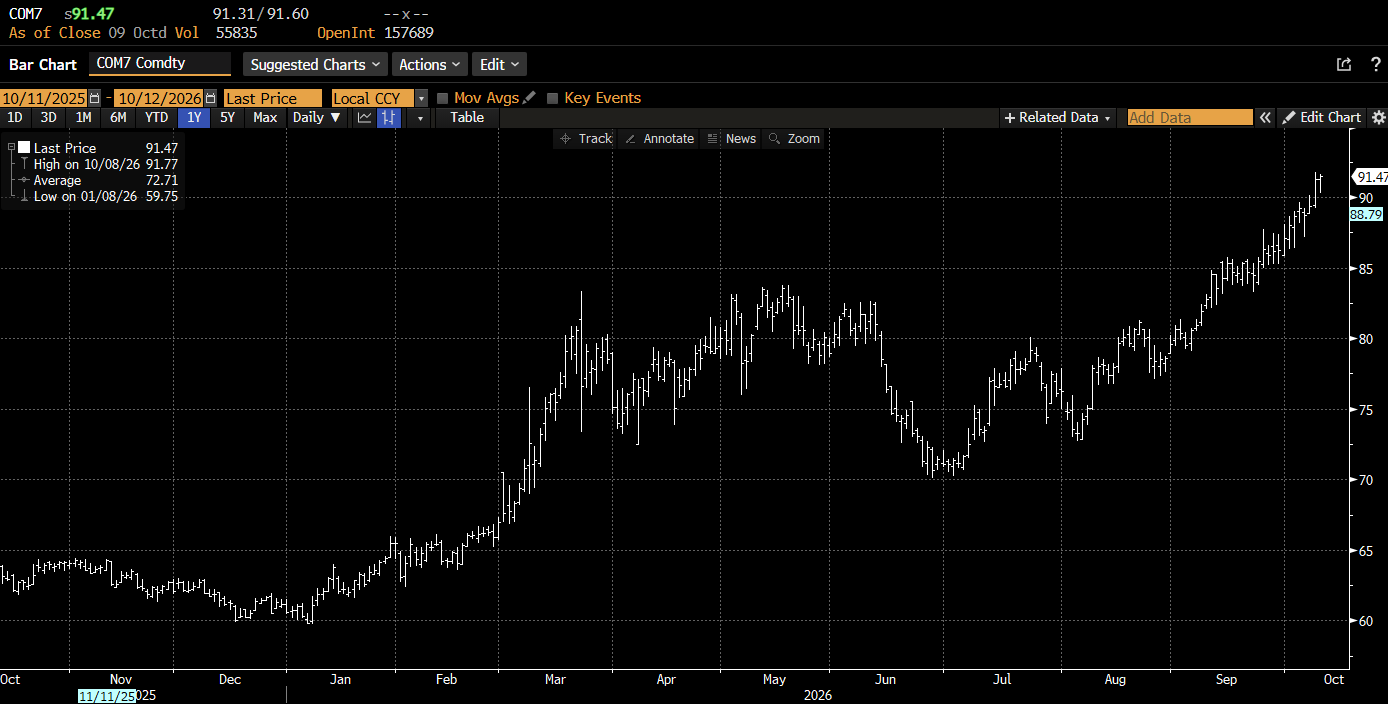
The war is obvious. The awful attack in Saudi Arabia, in addition to a supertanker reportedly hitting a mine this weekend, adds to evidence the war is metastasizing. I now count 17 sovereign nations involved and several non-state groups. Longer-dated oil contracts (below) hit fresh highs Friday on the close, which means investors believe this disruption will be protracted. Central banks targeting headline inflation are being forced to tighten. Risk premiums are rising.
AI is also cuspy. It helps to focus on a specific use case. As a macro investor, I look at individual companies as much to build a granular picture into the overall market as I do for a potential investment idea. For the case study, consider a new type of company—a cloud company I will call “A.”
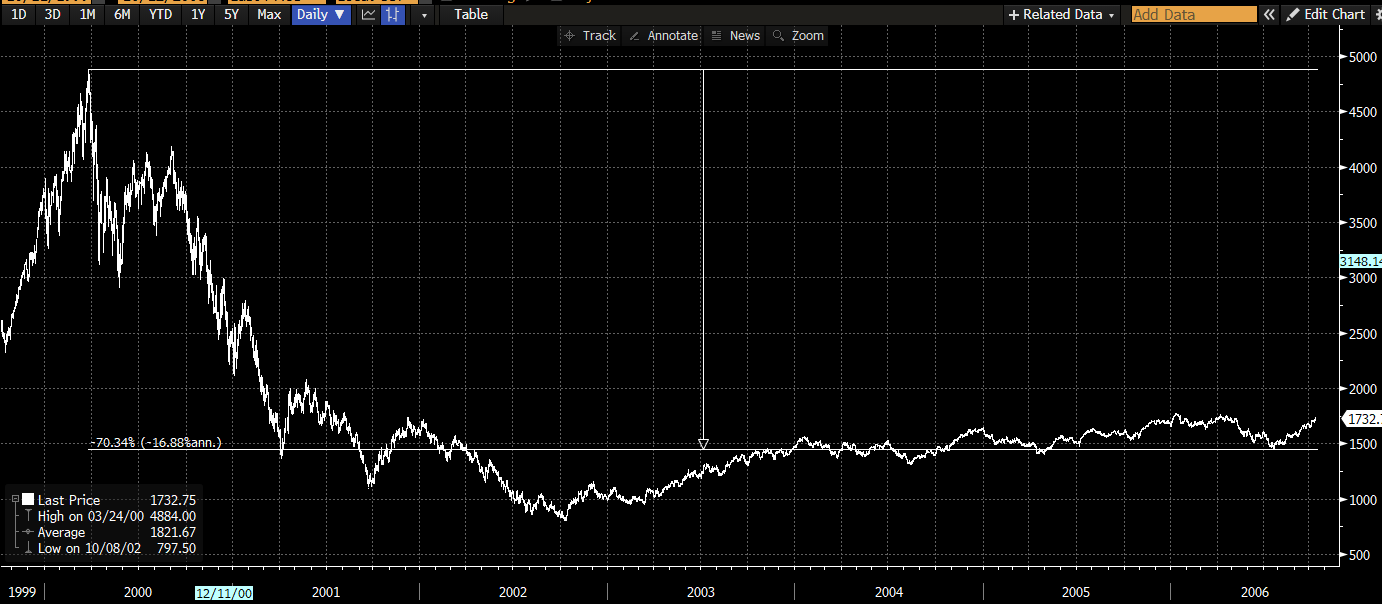
“A” exists because of the last big tech shift, the internet. High-speed internet allowed the creation of the cloud or, in plain English, the ability to move the big computers out of your office and home and put them in a warehouse that you access over the internet with a laptop. This idea took off in 2006 when Amazon introduced the notion that you pay as you go and only use the machines you need, as opposed to building it all in-house. In 2006, by the way, the Nasdaq was a cool 70% below its 2000 highs, as shown below.
Now companies want to add AI to that cloud mix. That’s where “A” comes in. Say you are a company, like Kate Capital, and you want to build your own AI product. You’d approach “A” and they have everything you need—racks of computers, fast chips, cables—and often at a cheaper price than Amazon or Google.
As long as demand for AI grows exponentially, all is well. For instance, if companies like Kate set up agents talking to agents 24/7, demand could grow fast. And maybe in the same way that the internet allowed the cloud business to come into existence and the iPhone allowed Waze to come into being untold profitable businesses are incubating right now. But no one knows what the growth rates will be and growth could come later, just as cloud computing came later.
Company A can’t wait for later because it doesn’t yet make money. Revenue is indeed growing fast. Analysts think revenues will grow exponentially in coming years. However, if you spend more than you earn, you borrow. Company A has borrowed about $10 billion so far. Early in 2030, the company needs to repay a lot of that. That is about 40 months away. Analysts don’t expect them to make money through 2027, so profits need to pick up sharply to repay the debt or investors will need to lend them more.
There are a number of companies in the AI story that are profitable monopolies, but quite a few, like A, that are more “story.” Build it and they will come. If doubts arise for whatever reason that the demand won’t come fast enough, the market’s moves will be swift and violent. The stampede could be triggered by a safety incident. It could be competition from China. It could be delays in opening data centers. It could be a political shift in Washington. But what we do know is that the shareholders and employees of A have a massive convex bet with little to no margin of error.
I am watching the bonds of A. If holders start to get wobbly, the stampede is near. The risk-reward is such that finding thoughtful ways to get ahead of the stampede may also have its merits.
Note to readers: No post Friday.