
Substack Library
GlossaryExporting A Higher Cost of Capital
October 4, 2026Not investment advice.
“The love of money as a possession — as distinguished from the love of money as a means to the enjoyments and realities of life — will be recognized for what it is, a somewhat disgusting morbidity…”. -Keynes, 1930.
It’s difficult for a casino to go bankrupt, but under the right leadership, possible. Today’s disruption originates from that same casino leadership in Washington, and coincides with and is amplified by Silicon Valley. The gale force churns like a hurricane, sucking in everything in its path.
AI is fueled by science-fiction visions of a futuristic world and by greed; regime change is an effort to coerce a, in this case, vicious foreign government. The result is a credit binge combined with an oil shock. The hurricane forces higher borrowing costs and a wave of inflation on economies that, unlike the US, are not growing above trend. Higher rates on foreign economies will depress growth going forward and possibly lead to a more meaningful equity correction.
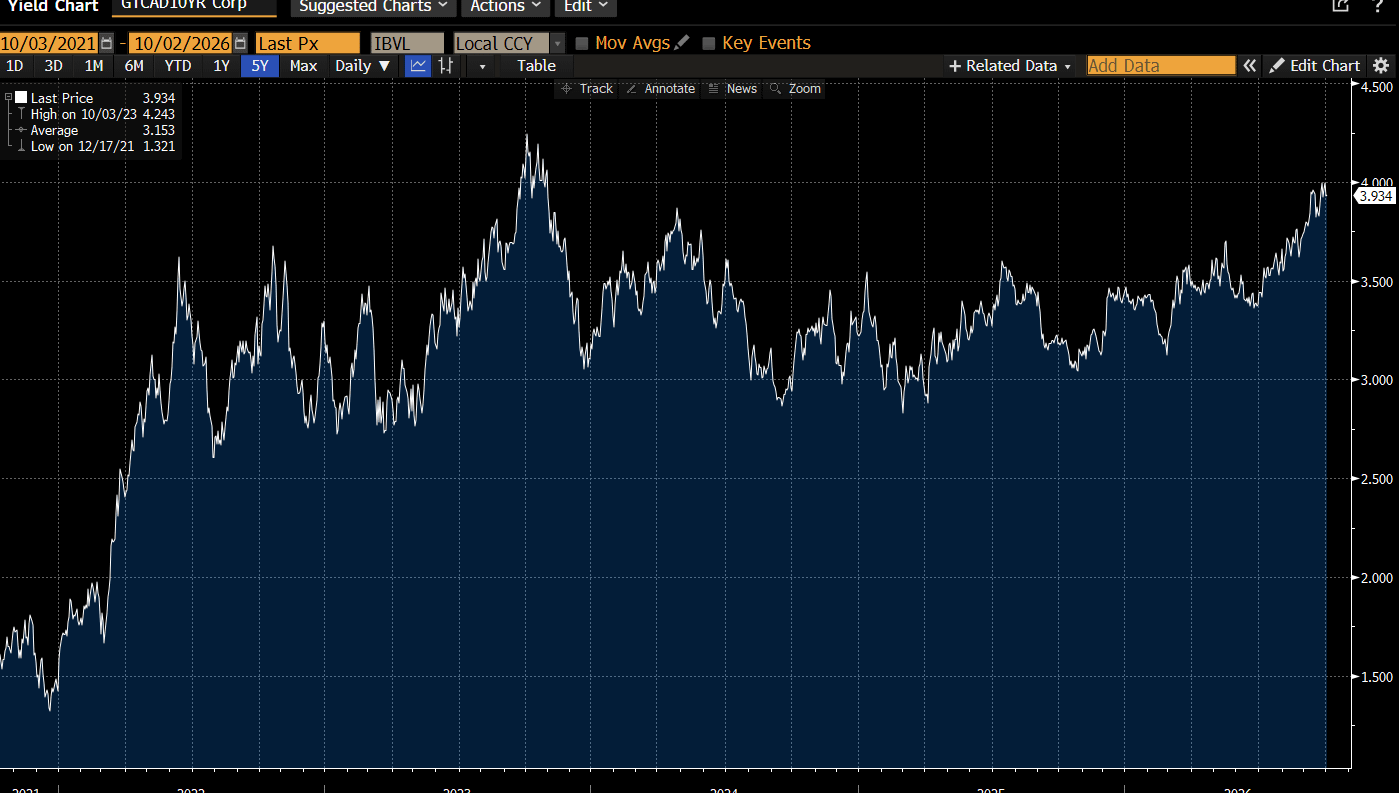
Consider a case study—Canada, though the same dynamic is also evident in countries from New Zealand to France, each with its own specific political twist. Canada’s bond yields have risen from about 3% to 4%, which is what you would expect in an inflationary boom.
The only issue is that the inflationary boom is in the US, not Canada. Below is growth.
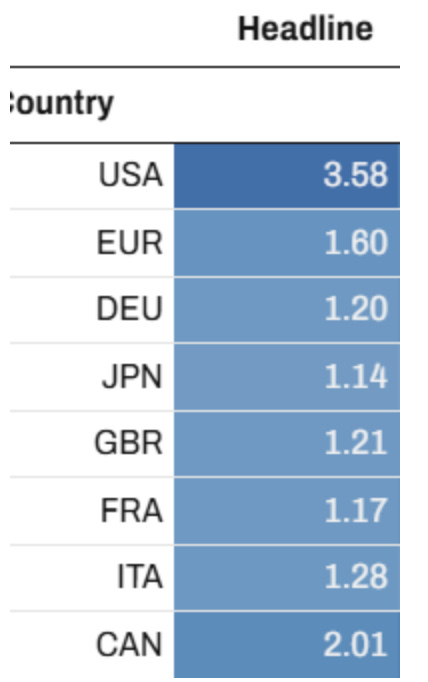
There isn’t much inflation either; core CPI in Canada is around 2%. This is because Canada is not a meaningful part of the AI boom and is also not running a big budget deficit. Canada’s budget deficit is around 2.4%, as opposed to about 6% in the US. The US’s efforts to suffocate cross-border trade further hamper Canadian growth. Canada’s bond-market reward for the US’s truculent, guns-and-butter policy is higher borrowing costs and slower growth. Yes, geography is unfair.
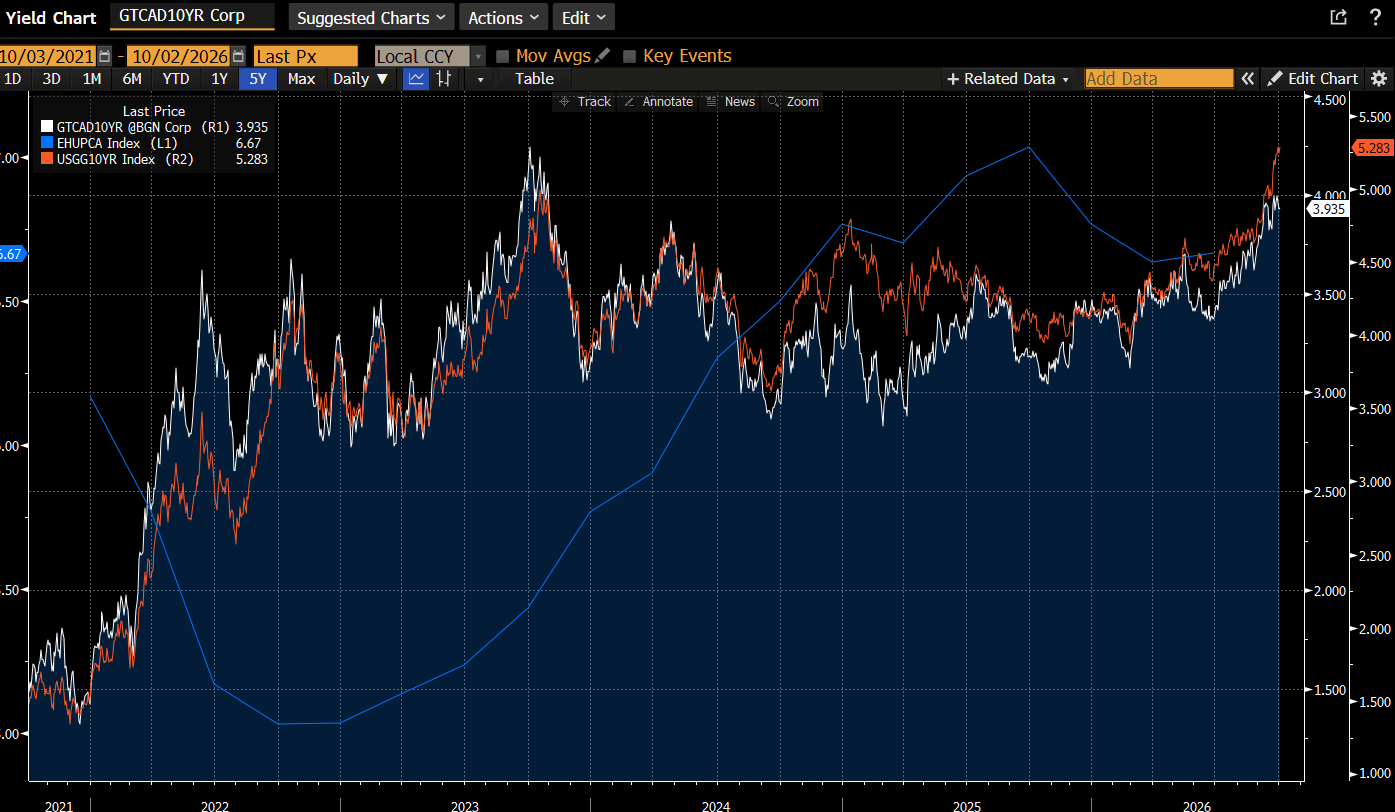
It can seem odd that bond markets trade in sync, but they do. In part this is because the AI debt issuance is global. In May, Google raised C$8.5 billion and in June Amazon raised C$14 billion, or about one-third of net new Canadian corporate issuance this year. Over time, however, markets often revert to pricing that accurately reflects local conditions. On the chart below I show yields in the US, Canada, and Canadian unemployment. As you can see, as US yields sell off, Canada sells off, even if Canadian employment conditions are tepid. Obviously, the US (orange line) has sold off more.
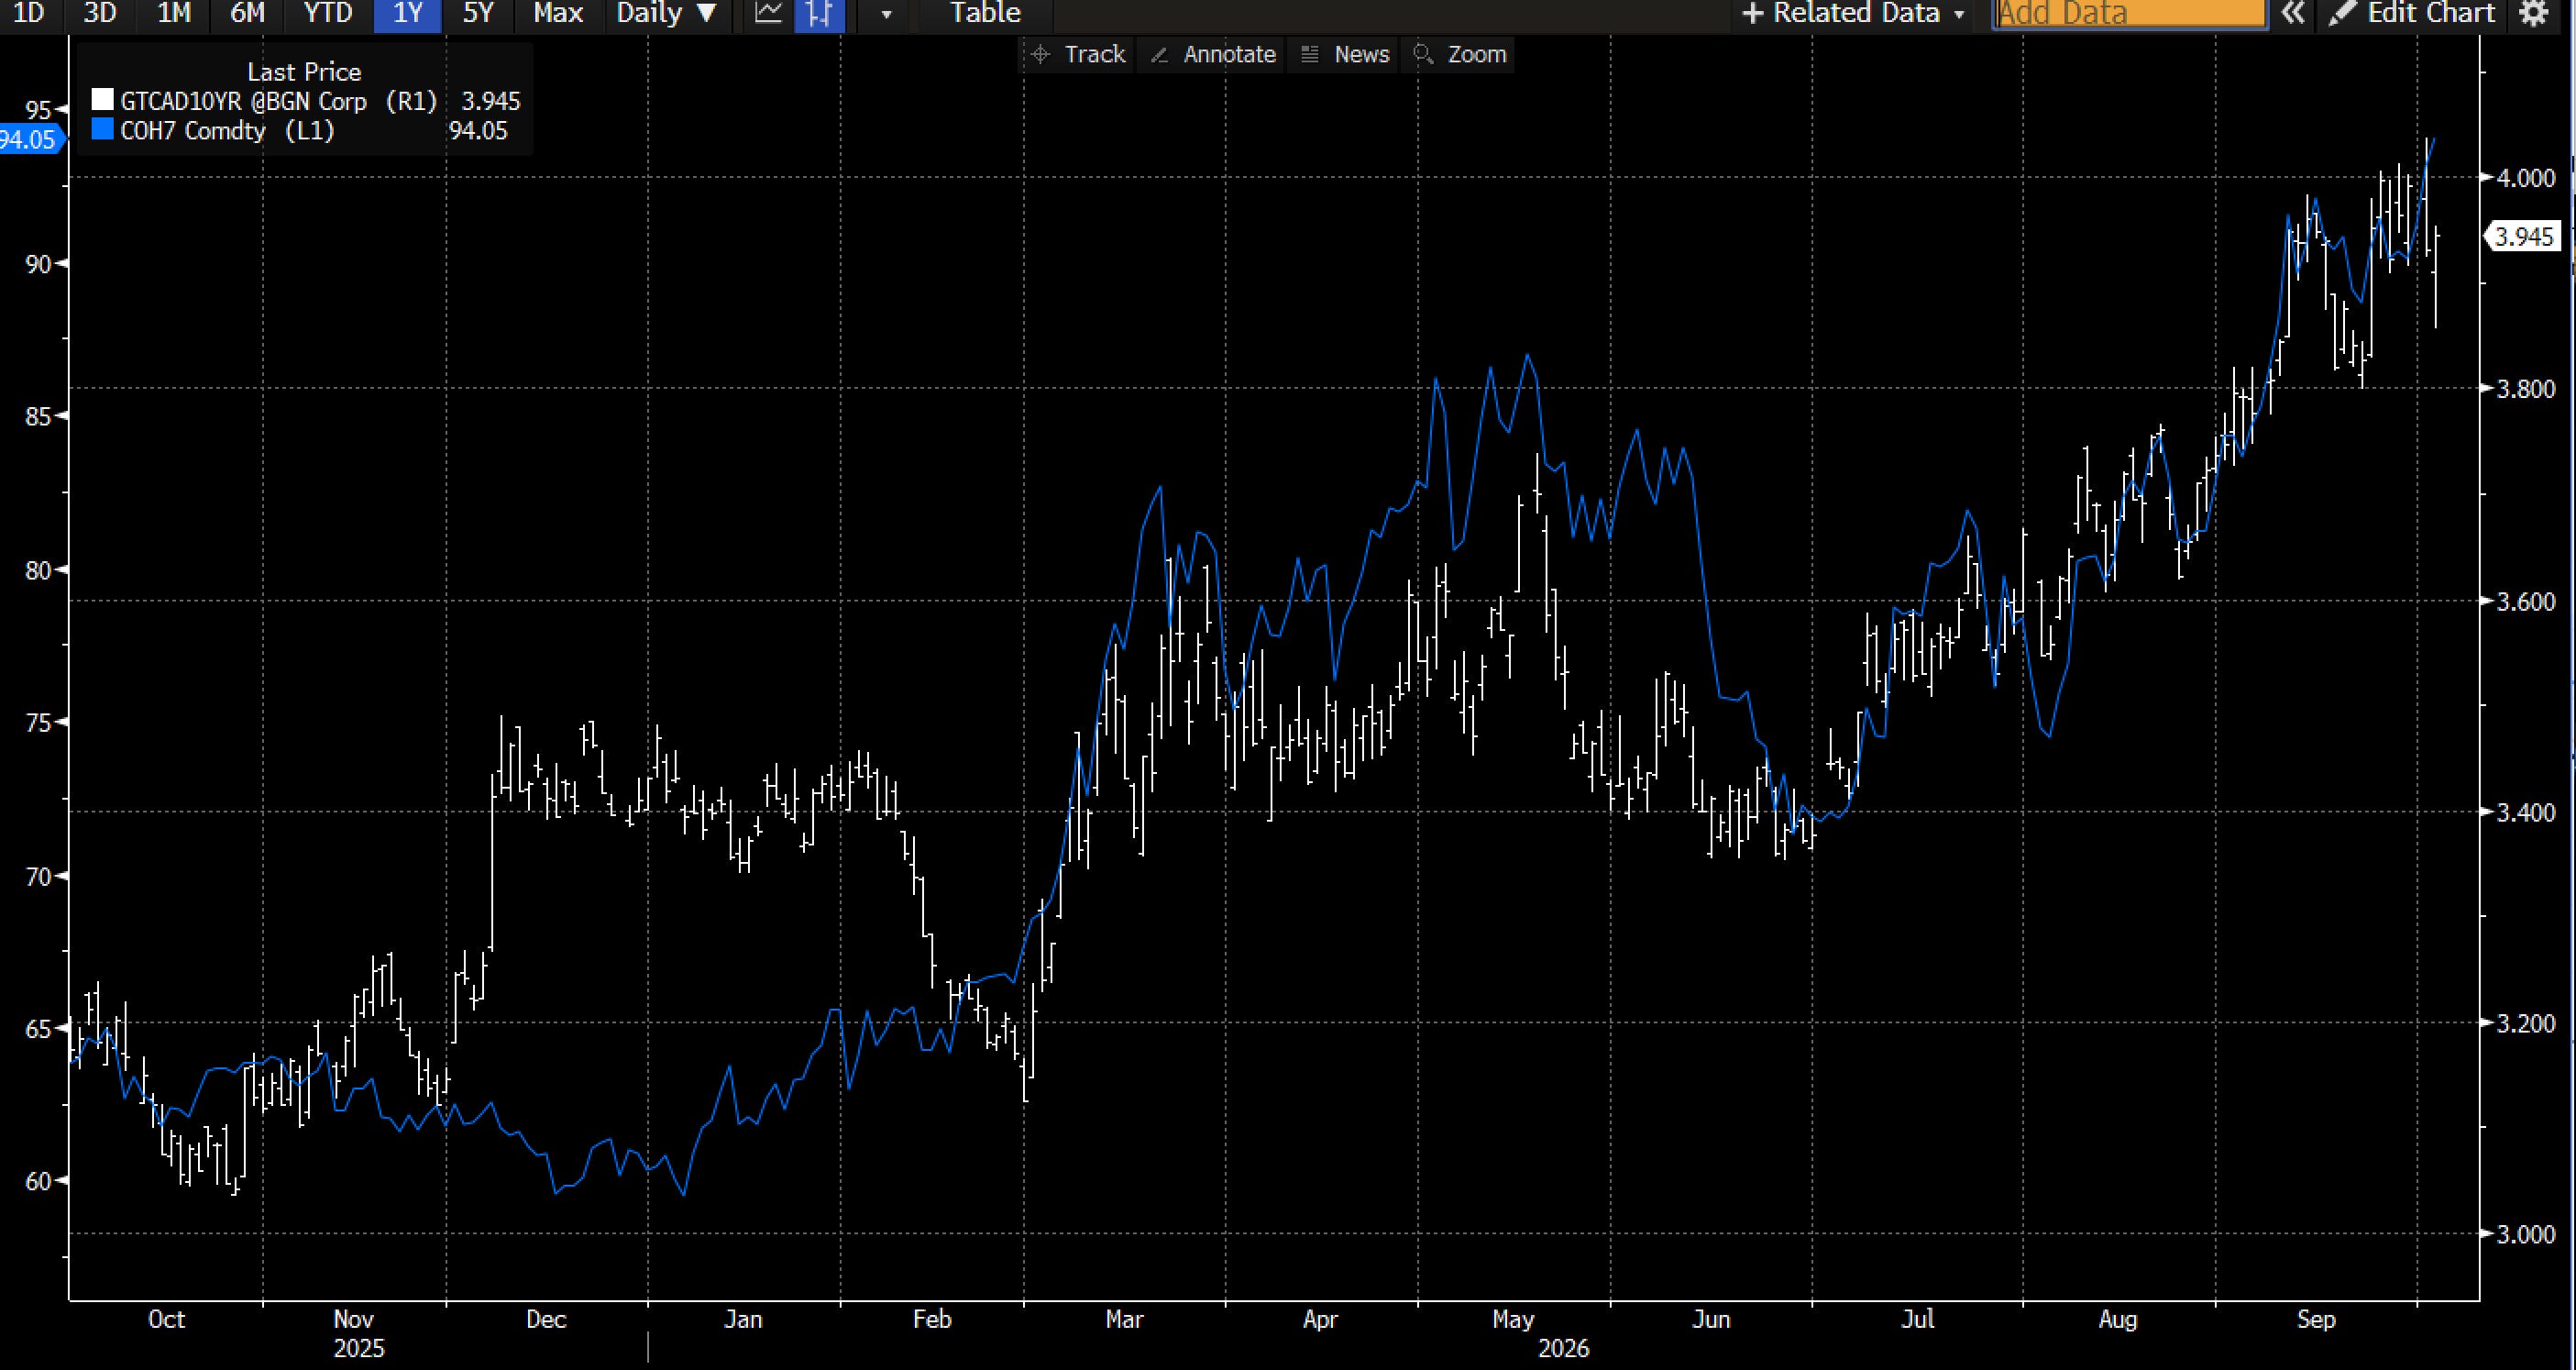
The war doesn’t help. Despite news that the oil is flowing, the IRGC is a difficult opponent and can choose to escalate. Our measures do suggest that more oil is flowing, but a supply deficit remains. Tehran realizes now that the US has few military options to conquer them; defense is easier than offense. Thus the risk premium will remain in energy prices. Below are oil prices and the Canadian 10-year bond.
As bond yields move higher, the risk premium on stocks has dropped. The logical next step is that prices reset, either with lower stock prices or with higher bond yields; depending on the country, we might get a little of each, though, of the two, stock prices look more vulnerable to me.
Note to readers: I have several trips coming up and will publish when I can rather than my regular Friday cadence.